Medical insurance can help individuals who prefer a simpler method of managing expenses related to medical procedures, hospitalization, surgeries, and other covered medical expenses. There are many different kinds of medical insurance policies, differing in price, premiums, deductible amounts, and various other factors.
When it comes to buy health insurance now, it is essential to be aware of the precise type of medical insurance policy needed. Individual policies are appropriate for one person. Family policies are better suited for a group of people who live in one household. Also, different types of policies, such as those that are provided by the employer as well as those provided by the government.
Understand What Health Insurance Covers
There can be a huge difference in health insurance policy in terms of the coverage options. The health insurance plans cover various services like hospitalization, doctor appointments, preventive care, drugs, emergency room treatment, laboratory tests done in the hospital, and special services.
You should always check the benefits of each plan before making the choice. Additionally, it is important to know if some of these services need referrals, pre-approval, or co-payment.
Compare Premiums and Out-of-Pocket Costs
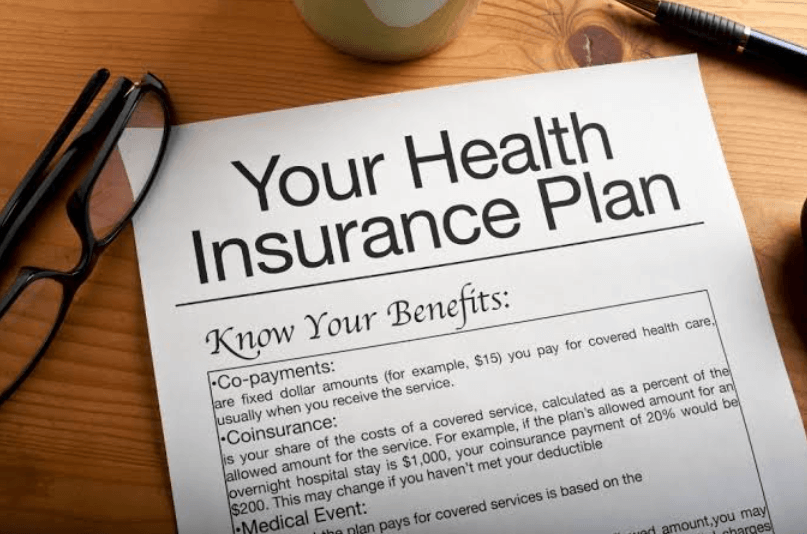
The premium is only one part of the total cost of health insurance. A plan with a low monthly premium may have higher deductibles, copayments, or coinsurance.
| Cost | What It Means |
| Premium | The amount paid to maintain insurance coverage |
| Deductible | The amount paid before certain insurance benefits begin |
| Copayment | A fixed amount paid for a covered service |
| Coinsurance | A percentage of covered costs paid by the policyholder |
| Out-of-pocket maximum | The maximum amount paid for covered services during a policy period |
Check the Provider Network
Health insurance policies may offer their holders a list of accredited physicians, institutions, treatment centres, and other medical service providers. Choosing in-network providers could potentially save you some money, depending on the health insurance programme.
Check whether your preferred physicians or hospitals are included in the network. People who require frequent visits to specialists should also ensure that such specialists are also on the list of participating doctors. One also needs to note that there may be differences in the network rules among different health insurance plans.
Review Exclusions and Limitations
Each individual health insurance policy defines the types of coverage provided. The exclusions in the policy may include certain services or treatments, providers, and situations.
It is important to go through the policy carefully and check for waiting periods, limitations on coverage, exclusions, terms regarding pre-existing health conditions, and conditions that must be satisfied before certain procedures can take place.
Consider Healthcare Needs
Choosing the right insurance policy depends partly on one’s anticipated health needs. A person who sees the doctor infrequently may have different preferences than someone who requires regular prescriptions, specialist hospital appointments and ongoing care.
Here are some things to consider when making your decision:
- What prescriptions and medical services do you currently receive?
- What types of medical visits do you expect to make?
- What are your family’s health care needs?
- Which hospitals and doctors do you prefer?
- What kinds of expenses are likely during the one-year duration of the plan?
- What are your estimated monthly and yearly expenses?
All these factors will help you find the right plans based not just on cost.
Understand Enrollment Rules
People can only get health insurance during specified enrollment periods unless they have a special enrollment period. There are various life circumstances that can affect enrollment, such as loss of previous insurance coverage, marriage, relocations, and more.
Application deadlines are also important – missing a deadline might result in a delay in getting insurance coverage or limit the options available for buyers. Those who want to buy have to find out the applicable rules for their insurance market.
See also: Why Hydration Plays A Role In Oral Health
Read the Fine Print Before Buying
The policy documents include crucial information that may not be available in the advertisements or in core outlines of the plans. It is essential to check the policy terms, conditions, exclusions, rules of filing claims, rules of renewals, and rules of cancellations.
Also, it is wise to compare a few plans on the basis of the same parameters. Rather than merely comparing premiums, the total payment, coverage, provider access, bonuses, and restrictions should be taken into consideration as well.
Keep Your Information Updated
Once a policy has been bought, it is necessary to ensure that the insurance and personal information stays up to date. Certain changes in address, household, income, and employment status may have a significant impact on eligibility for coverage by the insurance company.
Retain copies of policy papers and payment evidence, keeping insurance cards and important correspondence papers. Keeping records may simplify the way to prove coverage and address questions related to claims.
Having a clear idea of the existing alternatives will help in making the right choice to buy health insurance now, without missing out on any important details before making a final decision.
Conclusion
Choosing health insurance is an important financial decision which requires careful comparison of plans. Buyers must understand premiums, deductibles, networks of providers, exclusions, and the enrollment process, as well as their health care needs, in order to make this process easier. And instead of choosing the plan based purely on price, it would be wiser to look at the total cost of the plan and its coverage.